Written By: Stephanie Rojas | October 17, 2026
Time to Read 12 Minutes
Could a financing deadline arrive before traditional underwriting is ready? For Houston investors, timing can shape whether a deal works, but quick closing real estate loans Houston investors consider are not a guaranteed shortcut to closing. A faster process depends on preparation, clear communication, and progress through key milestones.
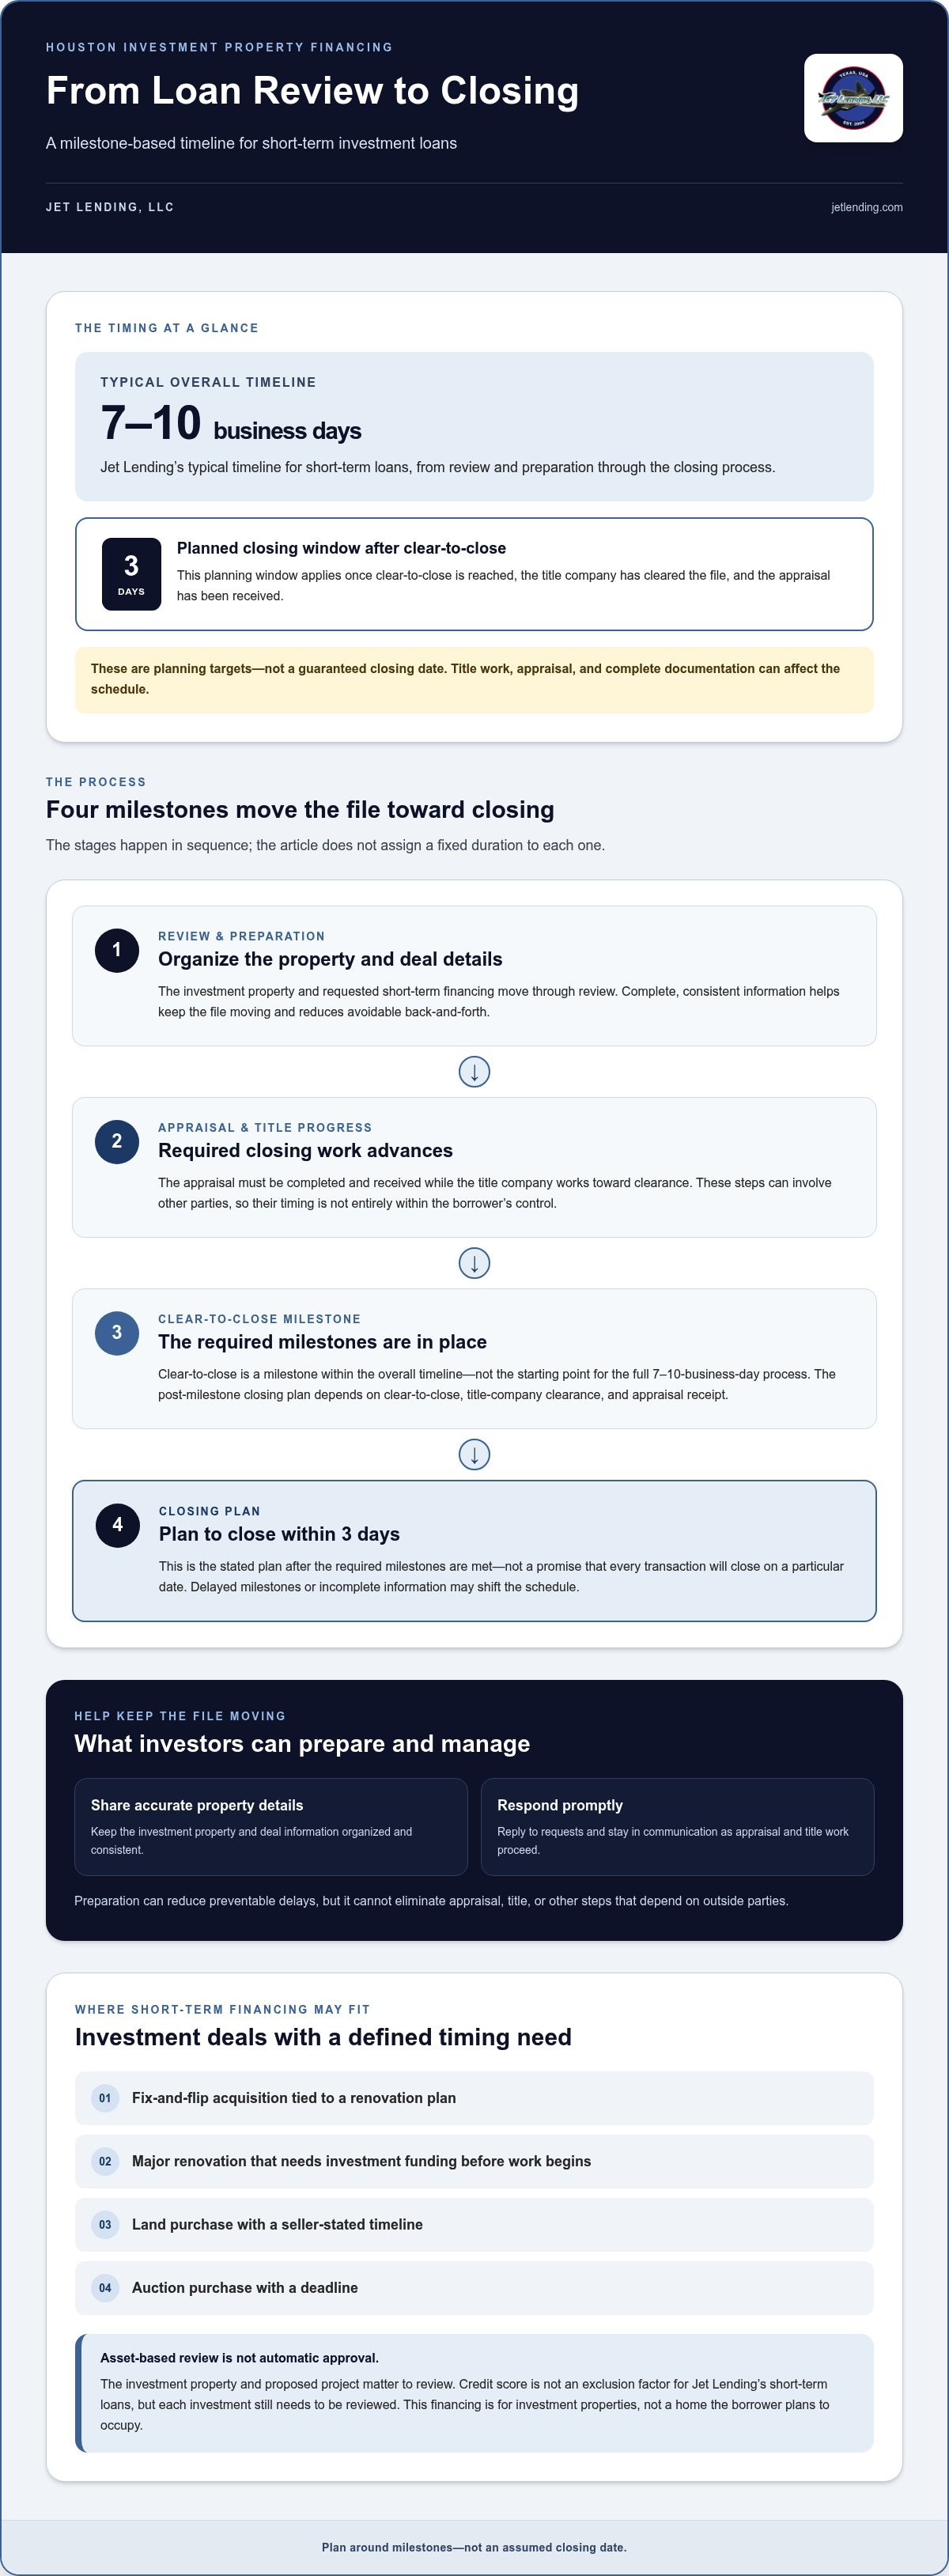
Before committing to an investment deal, it helps to know how the financing timeline is structured. Jet Lending’s typical overall timeline is 7-10 business days, with a plan to close within 3 days of clear-to-close. That is a planning target, not a guaranteed closing date. Title work, appraisal, and complete documentation all affect how smoothly a file moves forward.
This guide explains the main steps, what to organize to reduce preventable delays, and how asset-based short-term lending works for investment properties. It also covers how Jet Lending supports Houston real-estate investors as they evaluate their next move.
A Houston investor finds a fixer-upper with potential, but the seller has set a firm deadline. The investor needs more than a lender who says “fast.” A useful financing plan lays out the next steps, the information needed to review the deal, and which closing milestones depend on other parties.
Quick closing real estate loans Houston investors consider are generally short-term, asset-backed financing for eligible investment deals. These loans support projects such as property acquisitions, renovations, land purchases, and auction purchases. A faster process can help investors work within a deal’s timeframe, but it doesn’t mean a loan is automatically approved or that a closing date is guaranteed.
A tight purchase window can shape the financing plan from the outset. Investors may consider short-term financing for:
For each opportunity, compare the purchase deadline with the steps required to evaluate the deal and prepare for closing. A short timeline makes prompt responses especially valuable, but it doesn’t remove appraisal, title, or documentation steps. Treat the purchase date as a planning constraint, not proof that the transaction will close on schedule. This financing is for investment properties, not a mortgage for a home the borrower plans to occupy.
Asset-based short-term underwriting centers on the investment property and the deal. The property’s characteristics and the proposed project matter to the review. Credit score is not an exclusion factor for Jet Lending’s short-term loans, but that doesn’t mean every application qualifies. The investment still needs to be reviewed.
Asset-based review focuses on the property and investment plan, but it is not automatic approval. A faster process also depends on having relevant information ready and completing the required closing steps. Investors can help by keeping deal details organized and responding promptly to requests. Title and appraisal milestones may involve other parties, so those timelines are not entirely within the borrower’s control.
This distinction helps set realistic expectations. A quick-closing option can provide a financing path built around an investment opportunity, but a responsible plan accounts for both the purchase deadline and the work required to reach closing. For broader context on hard-money lending in Houston, use the existing “Hard Money Lenders Houston” investor guide as a companion resource.
A fast financing plan has more than one clock. Underwriting and file preparation happen before the final closing window, while title coordination and appraisal progress move the transaction toward clear-to-close. Treating these as separate stages gives investors a more useful timeline than assuming “quick close” means a single guaranteed date.
For Jet Lending short-term loans, the timeline is typically 7-10 business days overall, with a plan to close within 3 days of clear-to-close. The 3-day planning window begins after clear-to-close, title-company clearance, and receipt of the appraisal. It is a planning target, not a promise that every deal will close on a particular date.
Before clear-to-close, the investment property and requested short-term financing are reviewed while appraisal and title-company work progress. The appraisal must be received, and title coordination must reach clearance before the final closing plan applies. Complete, consistent property and deal information helps keep the review moving, but it cannot eliminate steps that depend on other parties.
Clear-to-close is a milestone in the process, not the starting point for the full loan timeline. The overall 7-10-business-day period includes earlier review and preparation. The plan to close within 3 days applies only after clear-to-close, title-company clearance, and appraisal receipt. If a milestone is delayed or information is incomplete, the schedule may shift.
Think of the process in stages:
Investors can support progress by sharing accurate property details, responding promptly to requests, and staying in communication as appraisal and title work proceed. This preparation can reduce avoidable back-and-forth, but it cannot control every outside timing factor. Build the purchase plan around milestones rather than assuming a closing date is fixed from the start.
When comparing quick closing real estate loans Houston options, distinguish the overall timeline from the period after appraisal receipt and title clearance. Jet Lending’s short-term investment loans are designed for investment-property financing, with a defined post-clear-to-close planning window.
A quick timeline only helps if the financing fits the property and investment plan. Compare the deal’s purpose, property type, closing dependencies, and next steps. A deadline matters, but it doesn’t establish whether a loan fits or guarantee that the transaction will close by that date.
Jet Lending’s short-term loans support investment purposes such as fix-and-flip acquisitions, major renovations, land purchases, and auction deals. The property and proposed investment plan determine the fit, not urgency alone. A property intended for a long-term rental may call for a different financing discussion. DSCR and Non-QM financing are separate long-term categories with their own terms and requirements. Don’t assume they share a short-term loan’s timeline or structure. For a broader explanation of the financing model, the “What Is a Hard Money Loan?” guide offers useful context.
Use this comparison to organize the deal details:
Deal purpose: A purchase tied to a flip, major renovation, land acquisition, or auction may align with short-term investment financing. Next action: State the intended project clearly.
Property type: A residential investment property, land, or commercial property can involve different preparation needs. Next action: Share the property’s use and relevant details.
Closing dependencies: Appraisal, title coordination, and property-specific requirements can affect preparation. Next action: Track outstanding milestones and keep information moving.
Long-term rental plan: A hold strategy may raise DSCR or Non-QM questions, distinct from short-term investment financing. Next action: Identify whether the goal is a short-term project or long-term ownership.
These categories are not interchangeable. Jet Lending’s short-term loans are for investment properties, not owner-occupied purchases. An investor planning a renovation and resale should describe that plan. Someone evaluating a long-term rental should make the financing horizon clear. The “What Is a Hard Money Loan?” guide explains the broader model, while the property-specific review considers the deal itself.
Some properties involve additional steps. A Phase 1 environmental report is required for land and commercial properties. Site history such as prior use as a gas station, dry cleaner, or oil well may be relevant to environmental review, though those examples don’t by themselves establish a hazard. Share known property details early so the appropriate preparation can move forward.
Insurance is another practical consideration. Hazard insurance is required for all properties. Flood insurance is required when a property is in a flood zone or has a flood history. For investors comparing quick closing real estate loans Houston, accounting for these property-specific requirements makes the closing plan more realistic.
Good preparation can reduce avoidable back-and-forth, even though it cannot control every appraisal, title, or closing dependency. Start with a clear picture of the investment and coordinate with the people involved as the file progresses. This gives your financing plan a stronger foundation without treating any single step as a guarantee of approval or a specific closing date.
Be ready to explain what you’re acquiring and what you plan to do with it. A fix-and-flip, major renovation, land purchase, or other investment project should have a clear purpose. Keep property details and relevant contacts easy to access, then stay responsive as appraisal and title work progress. Organized information helps the review proceed, but it doesn’t guarantee approval.
If you’re assessing a potential renovation or resale, Jet Lending’s “How to Analyze a Fix and Flip Deal” guide offers a framework for reviewing the deal. Use that analysis alongside financing preparation: a promising project still needs property details, title coordination, and appraisal milestones to move toward closing.
Property type can affect what preparation is needed. Surveys aren’t required for short-term lot-and-block loans. They are required for Non-QM long-term loans or meets-and-bounds properties. A Phase 1 environmental report is required for land or commercial properties. Identify the property’s characteristics early so these requirements can be considered as the file develops.
Hazard insurance is required for all properties. Flood insurance is required when a property is in a flood zone or has a flood history. Jet Lending doesn’t have a preferred insurer, and any referrals are unaffiliated with the company. Keep these conditions in view as you organize the deal. A realistic plan for quick closing real estate loans Houston investors pursue accounts for borrower readiness and milestones that other parties must complete.
A short-term investment loan works best when the financing approach, property, and project are considered together. Jet Lending is a Houston-based asset-based lender serving real-estate investors. Its short-term loans support investment purchases and projects, including fix-and-flips, major renovations, land acquisitions, and auction purchases. That local focus helps Houston investors consider investment-property financing in the context of their deal, without a promise of automatic approval.
Asset-based underwriting focuses on the investment property and deal. Credit score is not an exclusion factor for Jet Lending’s short-term loans, though every deal remains subject to review. In Texas, borrowers may close personally or through a business entity. The financing is for investment purposes, not owner-occupied home purchases or personal borrowing.
Jet Lending has funded over 4,000 loans, with over $650,000,000 total funded. The company is recognized by Forbes and was named Best Hard Money Lender for Customer Service in 2024, 2025, and 2026. These milestones reflect the company’s work with investors, while each new transaction still needs its own review and closing preparation.
Start with the property and the investment purpose. Identify whether the deal involves an acquisition, renovation, land, or another investment project, and gather updates on title coordination and appraisal. Clear information helps frame the financing conversation around the actual transaction and makes it easier to identify remaining milestones, rather than treating a desired closing date as certain.
Jet Lending’s stated timeline is typically 7-10 business days overall, with a plan to close within 3 days of clear-to-close. That 3-day plan follows clear-to-close, title-company clearance, and receipt of the appraisal. It is a planning target, not a guaranteed date. Outstanding milestones and timing outside the borrower’s control can affect the schedule. Investors considering quick closing real estate loans Houston can use these conditions to build a more realistic plan.
Before discussing a deal, gather the property details, intended investment use, and any known updates on title or appraisal progress. If you plan to close through a business entity, have that intended structure ready to discuss. Jet Lending does not provide legal advice and is not an attorney. Consult an attorney for legal guidance about your transaction or entity structure.
A seller’s deadline can create pressure, but your next move doesn’t have to be guesswork. Define the investment plan, organize what you know about the property, and identify which closing milestones remain. That gives you a clearer basis for deciding whether quick closing real estate loans Houston investors consider fit your opportunity and timeline.
Bring the specific deal into the conversation. A fix-and-flip, renovation, land purchase, or auction opportunity each has its own context. A focused discussion can help you consider the financing path and what to prepare next. Keep the schedule realistic: a target date is useful for planning, but it cannot replace completed review and closing steps.
With a clear plan and investment-focused guidance, you can approach the next opportunity with more confidence and make decisions at a pace that suits the deal.
Start by discussing your Houston investment deal with Jet Lending and outlining the milestones that remain.
Jet Lending’s overall timeline is typically 7-10 business days. The plan is to close within 3 days of clear-to-close, after title-company coordination and clearance and appraisal receipt. These are planning figures, not a guaranteed closing date. For quick closing real estate loans Houston investors are considering, compare the purchase deadline with the milestones still outstanding and leave room for steps that depend on other parties.
A credit score isn’t an exclusion factor for Jet Lending short-term loans because the underwriting is asset-based. That doesn’t mean every application is approved. The review focuses on the investment property and deal, so a Houston investor should be ready to discuss the property, project purpose, and transaction details. A low score alone doesn’t determine the outcome.
It depends on the financing and property description. A survey isn’t needed for a short-term lot-and-block loan. A survey is required for Non-QM long-term products or for a meets-and-bounds property. Identify which type of financing and property description applies to your Houston investment so the survey requirement is considered in the right context.
No. Hazard insurance is required for all properties, while flood insurance is required when a property is in a flood zone or has a flood history. Flood coverage isn’t a universal requirement for every investment property. Jet Lending doesn’t have a preferred insurer, and any referrals are unaffiliated with the company.
Yes. In Texas, borrowers may close in a personal name or through a business entity. This flexibility is specific to the Texas closing guidance and shouldn’t be assumed to apply in other states. Jet Lending isn’t an attorney and doesn’t provide legal advice. Seek independent legal guidance about how to hold title or structure an entity for a Houston investment.
For a Texas loan, the maximum loan amount is 70% of ARV, with repairs subtracted at closing. The example is: Purchase $40k + Repairs $20k = ARV $100k → Loan $70k → Funding at closing $50k → Out-of-pocket -$10k. This illustrates the ARV calculation and repair deduction; it doesn’t guarantee approval or mean every investment deal will have the same result.
Tags:

The "cheapest" interest rate in the 2026 Houston market is often the most expensive choice an investor can make. While a lower conventional rate looks good on paper, it doesn't matter if you lose the...

In Houston’s fast-moving 2026 market, the most expensive loan isn't the one with the highest interest rate; it's the one that fails to close on time. You've likely watched a perfect flip or rental...

Why are you still waiting weeks for a bank appraisal while your competitors are already swinging hammers on the best off-market deals in Harris County? In a market where average flip profits...