Written By: Stephanie Rojas | November 18, 2026
Time to Read 12 Minutes
A bank isn’t the only route to financing an investment property. Real estate investor funding without banks can include hard-money loans, private lenders, crowdfunding, and seller financing, with different trade-offs for budget, credit, and risk. The right fit depends on the deal, the funds you can bring, and how quickly you need to repay.
It’s understandable to focus first on approval and available cash. But fast funding may come with a shorter repayment period, while pooled investments can mean less say in property decisions. This guide compares how each route works so you can identify the trade-offs that fit your investment plan.
You’ll learn what to weigh when comparing hard-money loans for flips, private money, crowdfunding, and seller financing. You’ll also get a practical framework for matching funding to your budget and credit profile, then see how short-term loans and an investment property calculator can support deal analysis.
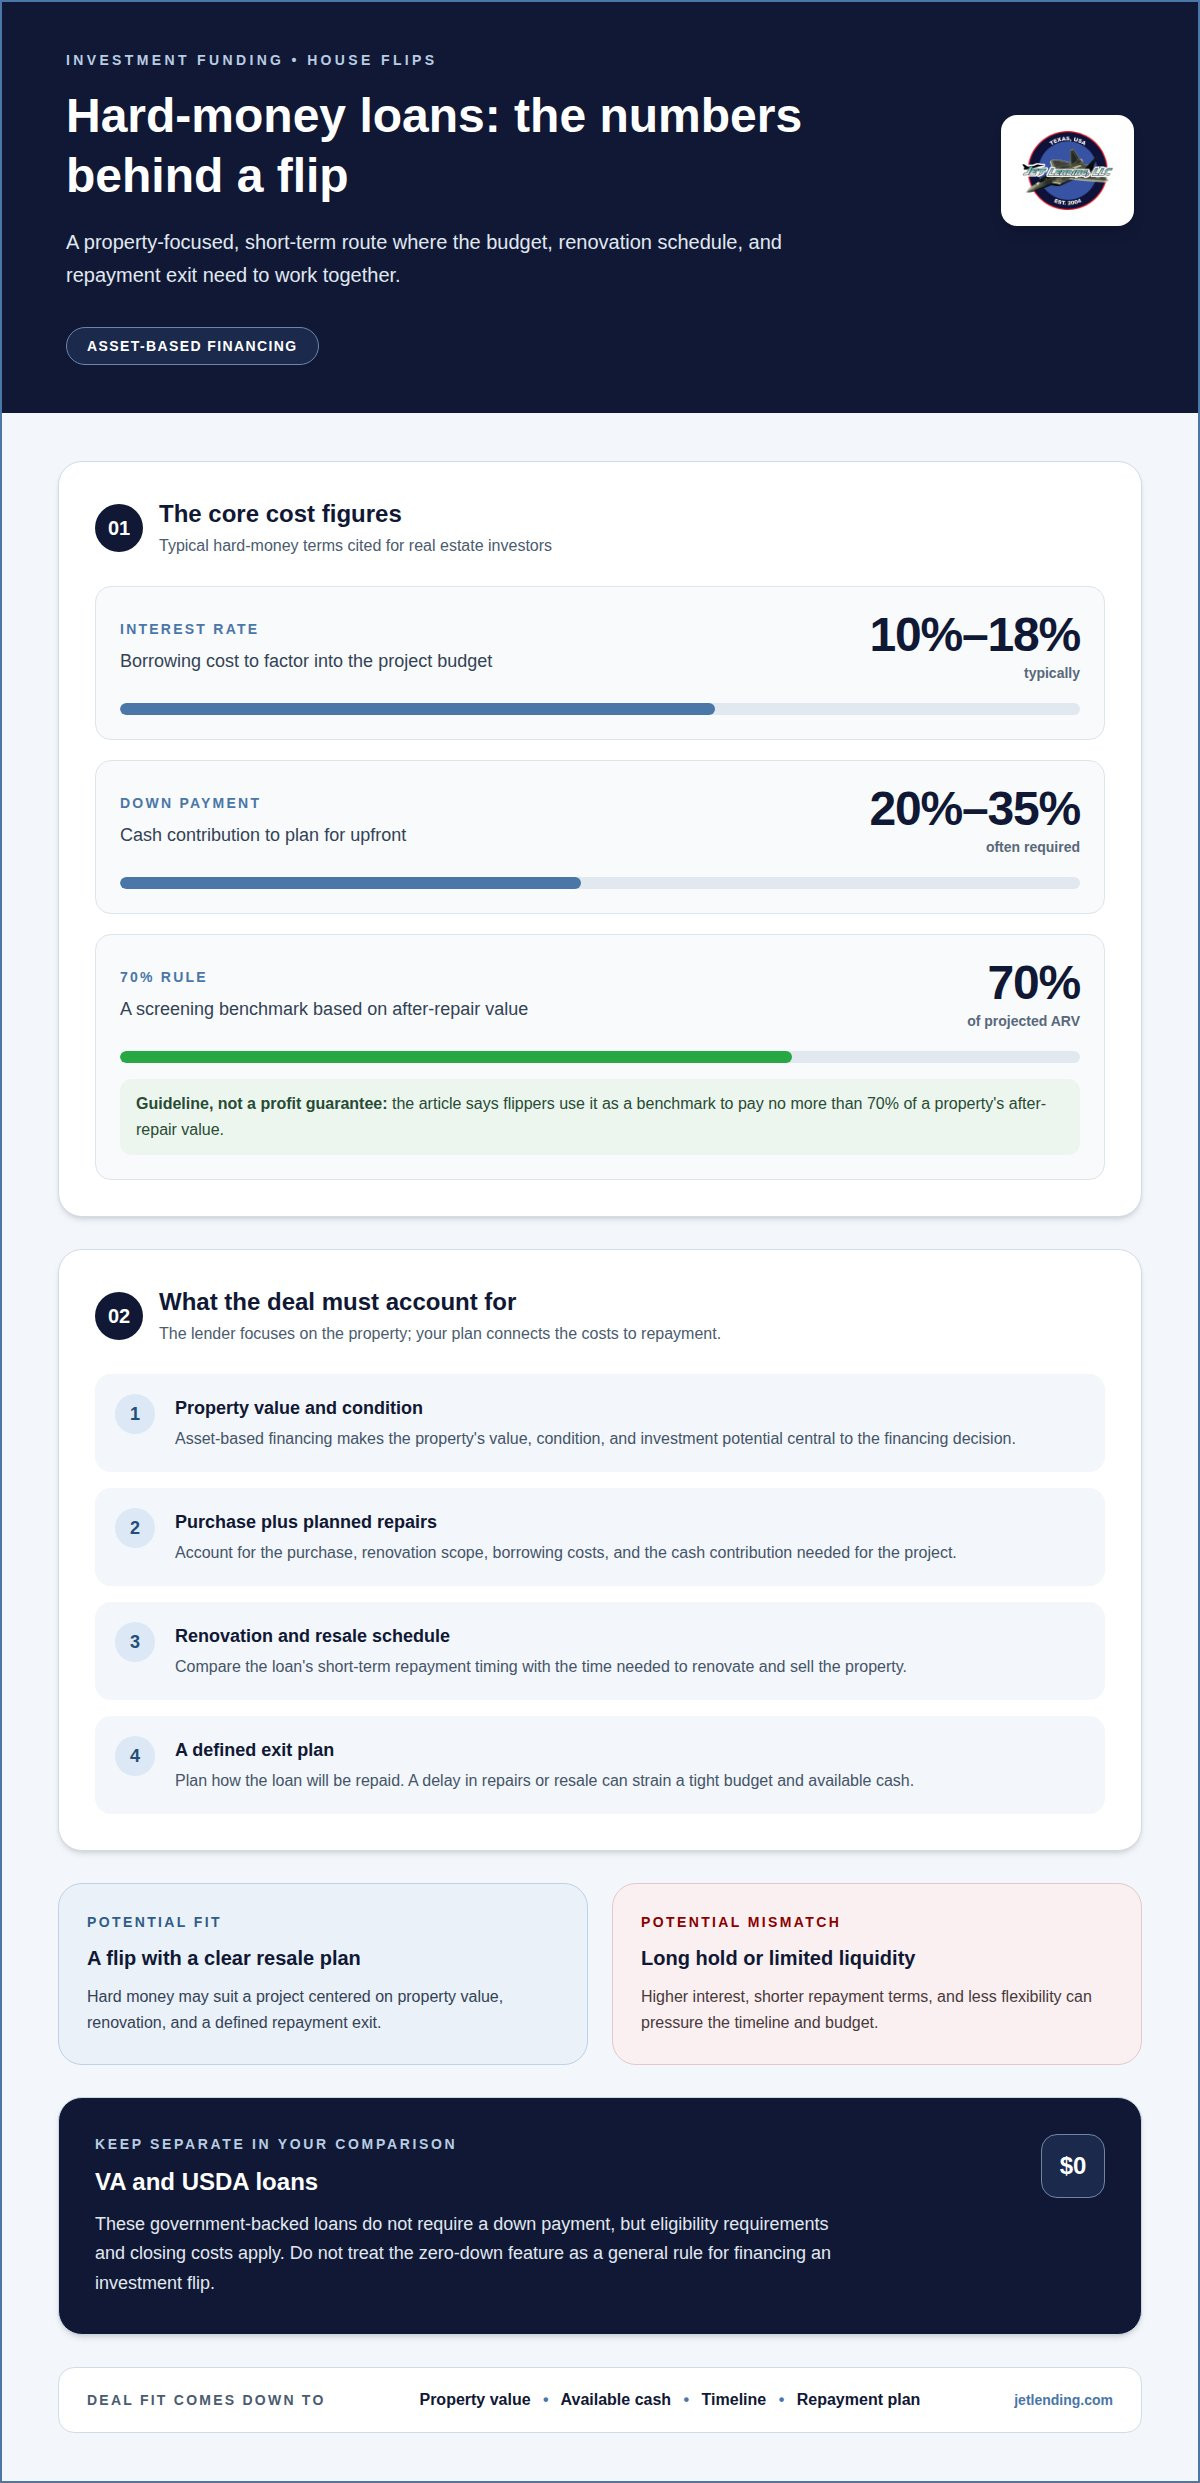
Hard-money loans are asset-based financing intended primarily for real estate investors, especially house flippers. The lender focuses on the property’s value, making its condition and investment potential central to the financing decision. For a Houston flip, connect the purchase, planned repairs, and resale strategy before choosing this route. Because the loan is short-term, the exit plan is part of the deal, not an afterthought.
Budget carefully for the borrowing cost and cash contribution. Hard-money loans typically carry interest rates of 10% to 18% and often require a down payment of 20% to 35%. Those figures affect both the amount of cash needed upfront and the project’s carrying costs. A tight budget can become strained if repairs or resale take longer than expected. Compare the planned repayment timing with the property’s renovation and sale schedule before committing.
The 70% rule offers flippers a screening benchmark: pay no more than 70% of a property’s after-repair value. It is a guideline, not a guarantee that a project will be profitable. The purchase price, repair scope, financing costs, and resale assumptions all influence the deal. For example, if the projected after-repair value does not leave enough room for renovation and borrowing costs, the property may not fit the investor’s budget. A strong projected resale value alone does not remove execution risk.
Government-backed loans need a separate look. VA and USDA loans do not require a down payment, though eligibility requirements and closing costs apply. That feature should not be treated as a general rule for funding an investment flip. Eligibility matters, and a zero-down feature does not establish that a particular investor or property qualifies. Keep government-backed financing distinct from hard money when comparing funding routes.
Hard money can suit a flip when the deal depends on property value and a defined resale plan. It may be a poor match for a long-term investment or an investor with limited liquidity. Higher interest rates, shorter repayment terms, and less flexibility can pressure both the budget and timeline. Before choosing this approach, map the purchase and renovation period against available cash and planned repayment. This makes it easier to see whether the project can carry the loan through to its exit.
A professional lender evaluates an investor’s financing needs by considering the property, proposed deal, available funds, and repayment plan. Private lenders may also consider factors beyond credit score and financial history, so the full project can matter alongside the borrower’s credit profile.
“Private money lender” can describe an individual or private source financing a real estate investment outside a traditional bank loan. The lender and borrower agree on terms for a specific deal. Terms and evaluation criteria can differ, so don’t assume one private lender’s approach applies to every Houston property or investor.
Start the discussion with the property and investment purpose. A lender needs to understand whether the plan involves buying, renovating, holding, or reselling the property. The budget should account for the purchase and planned work, while the repayment plan should explain how the loan will be repaid. These details tie the requested financing to the project rather than treating it as an isolated credit application.
For example, an investor with a strong property plan but a nontraditional income source may want a lender to consider more than conventional credit measures. The lender may weigh the property and deal alongside the borrower’s financial background. That doesn’t mean credit history is irrelevant; it means private lenders may assess additional factors as part of their decision.
Before choosing this route, make sure the financing aligns with the project timeline and expected cash flow. Clarify the repayment structure, the lender’s expectations, and how the plan accounts for delays or changes. Those details matter if renovation takes longer than planned or a resale is postponed. A private lender may suit an investor whose needs call for a broader review, but clear terms are essential to understanding the commitment.
Look for individual or private sources that finance real estate investments, then discuss the property, investment purpose, budget, available funds, and repayment plan. Vet each lender by clarifying its evaluation criteria, repayment structure, expectations, and how the financing would handle project delays or changes.
Some investors may also compare private financing with hard-money loans. These asset-based loans are intended primarily for real estate investors, especially those doing fix-and-flip projects, and focus on the value of the property being purchased. This can be relevant when the investment centers on acquiring and reselling a property, but it doesn’t establish whether a loan suits a particular deal. Discuss how the property’s value relates to the proposed project, and consider whether the repayment terms fit the investment plan.
Hard-money loans often have higher interest rates, shorter repayment terms, and less flexibility, which can make them unsuitable for long-term investments or borrowers with limited liquidity. Compare those features with the project timeline and funds available to meet repayment obligations. If the plan depends on holding a property longer or available cash is limited, consider whether the terms could create a mismatch. Ask the lender to explain the repayment structure and assess whether the project can accommodate it, including if the planned resale or another repayment source is delayed. Weigh the financing against the specific property and investment purpose before proceeding.
Real estate crowdfunding brings multiple people together to fund projects collectively. For a Houston investor seeking project capital, it can be another route to consider beyond borrowing from one lender. But crowdfunding is not automatically a conventional loan to the property buyer. The project structure determines how funds are used and what participants receive. Understand that structure before treating pooled funding as a fit for a purchase or renovation plan.
Crowdfunding platforms connect participants with real estate projects seeking investment. Each platform presents its own opportunities and terms, so don’t assume every listing works the same way. Read the project description for its purpose, timeline, and proposed use of funds. Then compare those details with the property’s needs. A project seeking investment for development may not fit someone who needs a direct loan to acquire a specific house.
The main appeal is pooled capital: no single participant has to supply the entire project’s funding. That shared approach can also mean less control over property-management decisions. If the project operator makes day-to-day choices, participants may have limited input on leasing, maintenance, or timing. For an investor who wants direct control of a Houston property, that trade-off deserves careful thought. Access to a project is not the same as managing the asset.
Returns can vary, and project delays can affect the expected timeline. Renovation, construction, or a property sale may not proceed exactly as planned. Before committing, compare the proposed holding period with your own need for access to funds. Consider whether a delay would disrupt your wider investment budget. Don’t rely on one projected outcome as if it were assured. The project’s plan and its ability to execute both shape the result.
A practical way to assess a crowdfunding opportunity is to review three points: the project’s purpose, your level of control, and the timeline for returns. For example, an investor comfortable backing a shared project may accept limited decision-making in exchange for participating without managing the property directly. Someone who needs a clear loan amount and repayment structure may find that arrangement less suitable. The right comparison depends on what the capital needs to do.
Crowdfunding platforms can broaden how real estate projects gather capital, but they don’t remove project risk. Treat project details as a starting point for understanding the arrangement, not a substitute for knowing how funds are deployed. Compare the funding structure with the property, your budget, and your desired role. If direct control and a defined borrowing arrangement matter most, weigh those priorities against the shared-investment model before choosing.
Seller financing lets the property’s seller lend directly to the buyer, with negotiable terms. For a Houston investor, this can create room to discuss payment timing and repayment structure directly with the seller. Traditional bank approval can take time, potentially costing investors time-sensitive purchase opportunities. Seller financing offers a different path, but the seller must be willing to provide it.
The availability of seller financing can vary with market conditions and the seller’s willingness to offer it. That limits how often investors can rely on seller financing. If a seller is open to it, the parties can negotiate terms around the property and transaction. The opportunity still needs to fit the buyer’s budget and repayment plan, rather than simply seeming more flexible than a bank loan.
Non-bank options vary in structure. Crowdfunding pools funds from multiple participants, and investors may have limited control over property-management decisions while facing project delays or variable returns. Peer-to-peer loans connect borrowers with lenders through a lending arrangement, while a private lender evaluates a particular investor and deal. Compare who supplies the capital, who controls decisions, and how repayment works before choosing.
Investors may also consider a HELOC or cash-out refinance, which use equity in an existing property, or retirement funds as a source of investment capital. A HELOC or refinance is still credit secured by property, so it is not necessarily funding without a bank. Using existing assets can put them at risk if the investment plan falls short.
Local conditions matter because seller financing depends on an individual seller’s willingness and negotiated terms. In Houston, a seller facing strong competition may be less inclined to offer financing than one seeking a different kind of transaction. State and local markets also shape the available properties and terms parties may negotiate. Consider the specific seller, property, and deal rather than assuming one financing structure is common everywhere.
Flexibility can help match financing to a property, but it doesn’t remove repayment risk. A seller-financed buyer still needs a workable payment plan; a crowdfunding participant may have less control; and a HELOC puts existing property equity at stake. Compare the funding source, decision-making control, repayment obligations, and downside exposure. This can reveal whether a flexible arrangement truly fits the investment or merely shifts risk elsewhere.
The broader lending backdrop also matters. After the 2008 financial crisis, banks became more risk-averse, making financing harder for some borrowers with unconventional income sources. For those buyers, a seller willing to discuss financing may be worth considering, but willingness alone does not make the arrangement suitable. Assess whether the negotiated payments fit the buyer’s income and obligations, and weigh the risk of relying on a repayment plan that may leave little room for disruption.
Suitable funding depends on the project, available cash, credit profile, and repayment plan. A professional lender evaluates those factors alongside the property and the investor’s financing needs. Hard-money loans may fit a flip; private lenders may consider factors beyond credit score and financial history. Crowdfunding pools investment, while seller financing depends on a willing seller.
Start with the deal’s purpose and timeline. A Houston investor planning renovations and resale needs financing that fits the project’s expected schedule. A longer-term hold calls for a repayment plan that can work beyond a quick sale. The lender considers how the requested funds relate to the property and how the investor plans to repay them.
There isn’t one credit score, experience level, down payment, or collateral requirement shared by every alternative lender. Private lenders may consider more than credit history, while hard-money lenders focus primarily on the property’s value. U.S. investment properties typically require a down payment of 15% to 25%; a particular non-bank option may assess the deal differently.
Credit still matters in context. Traditional banks commonly require strong credit histories, substantial down payments, and steady employment. An investor with unconventional income may therefore explore other routes, but that doesn’t mean every non-bank lender ignores credit or financial history. The property, available funds, and repayment plan can also shape the evaluation.
To arrange financing, give the lender a clear picture of the property and proposed investment. Explain the intended use of funds, available budget, project timeline, and expected repayment plan. Relevant credit and financial-history details help the lender understand the borrower’s position. For a Houston renovation, describe the planned work and resale or hold strategy rather than presenting only the purchase price.
An investment property calculator can help organize deal assumptions, including potential value and project expenses. Use that analysis alongside the lender’s review, not as a substitute for assessing repayment capacity. If the budget leaves little room for delays, a short-term structure may increase pressure. If the plan relies on pooled investment or seller participation, control and availability are key trade-offs.
Compare each option by asking what risk it places on your budget, what role you retain in property decisions, and whether repayment matches your timeline. This framework helps distinguish financing that fits the deal from an option that merely appears accessible. A lender can then match the project details and borrower profile to the structure under consideration.
Jet Lending, LLC helps real estate investors assess funding needs through Short-Term Loans and an Investment Property Calculator. Use these options when evaluating an investment property and considering financing alongside the deal’s projected numbers.
The calculator can help organize property assumptions for your analysis, while a Short-Term Loan may suit an investment that calls for short-term financing. Consider the purchase, planned use, budget, and repayment strategy together. This gives you a clearer basis for deciding whether short-term funding fits the project.
For a straightforward conversation about your real estate investment funding needs, contact Jet Lending, LLC.
Choosing real estate investor funding without banks is not just about finding capital. The financing also needs to support your investment plan, fit your available budget, and leave a clear path to repayment. Before moving forward, identify the project’s priorities and decide which trade-offs you can accept. That gives your next funding conversation a practical starting point.
Keep the property’s role in focus. Financing should make sense alongside the investment timeline and your broader goals, not distract from them. If you’re weighing a Houston opportunity, bring your project details and financing questions into one discussion. A clear picture of what you want to accomplish can help shape a focused next step.
Take the next step with a plan that reflects your investment priorities. Thoughtful preparation can help you move forward with greater clarity and confidence.
Hard-money loans use the investment property as the main basis for financing, and typically carry interest rates of 10% to 18%. Repayment periods are often shorter than conventional mortgages, so the planned sale or refinance matters. Fees and other terms vary by transaction. Before signing, review the written agreement for payment dates, payoff conditions, and any charges that may apply, including extension or default fees.
With seller financing, the property seller lends directly to the buyer, and both parties negotiate the financing terms. For example, they can discuss the down payment, payment schedule, payoff date, and what happens if payments are missed. Put the agreed terms into the transaction documents and understand how they affect the property transfer. Since sellers rarely offer this arrangement, treat it as a deal-specific opportunity, not a dependable funding plan.
Key risks include contract obligations, tax consequences, and losing collateral after default. In Texas, a missed payment or other breach can put the pledged property at risk of foreclosure, depending on the loan documents and applicable process. Tax treatment can vary with ownership, income, expenses, and transaction structure. Keep loan and property records organized, understand the default provisions before signing, and consult a Texas real estate attorney and tax professional about your specific transaction.
Tags:

A foreclosure deal can look like a bargain until the funding timeline, repair budget, or exit plan stops adding up. The key question isn’t simply whether hard money for foreclosure purchases Houston...

A long-term rental loan may be the wrong first move for a Cypress property that needs work. The right investment property financing Cypress TX investors pursue depends on the deal’s timeline and...

What if the financing that gets you into a Houston investment property becomes the biggest risk to getting out? A bridge loan can connect an acquisition or rehabilitation project to its next...