Written By: Stephanie Rojas | October 05, 2026
Time to Read 12 Minutes
What if you could make a strong Houston offer without waiting for a bank’s full approval process? For investors competing with cash buyers, bridge loans for real estate investors Houston can provide short-term, asset-backed capital to move on an opportunity while planning the property’s next phase.
Speed matters, but financing a deal is about more than getting to closing. You also need to understand how the property and exit strategy shape the loan, how rehab costs fit the budget, and what happens when it’s time to refinance or sell. A clear plan helps you pursue an opportunity without losing sight of the numbers.
This guide explains how bridge financing works for Houston investment properties, what lenders may evaluate, and how to weigh loan terms, rehab needs, and exit options. You’ll also learn how Jet Lending’s short-term, asset-backed financing and investment property calculator can support your deal analysis. Use these fundamentals to turn a promising lead into a financing plan built around your investment goals.
A real estate bridge loan is short-term, asset-backed financing that helps an investor acquire or improve a property before moving to a longer-term financing solution or selling it. The “bridge” is the gap between acting on an opportunity and reaching the planned exit. For a foundational overview, see What is a bridge loan?
Unlike a traditional 30-year mortgage, a bridge loan is structured for a shorter investment timeline, not decades of scheduled payments. Some are structured as interest-only, meaning the borrower pays interest during the loan term and repays principal when the property is sold or refinanced. That structure can leave more cash available for repairs and other project expenses, but the principal still needs a clear repayment plan. Bridge loans for real estate investors Houston can fit situations where the property’s condition, purchase timeline, or investment strategy doesn’t suit a conventional mortgage process.
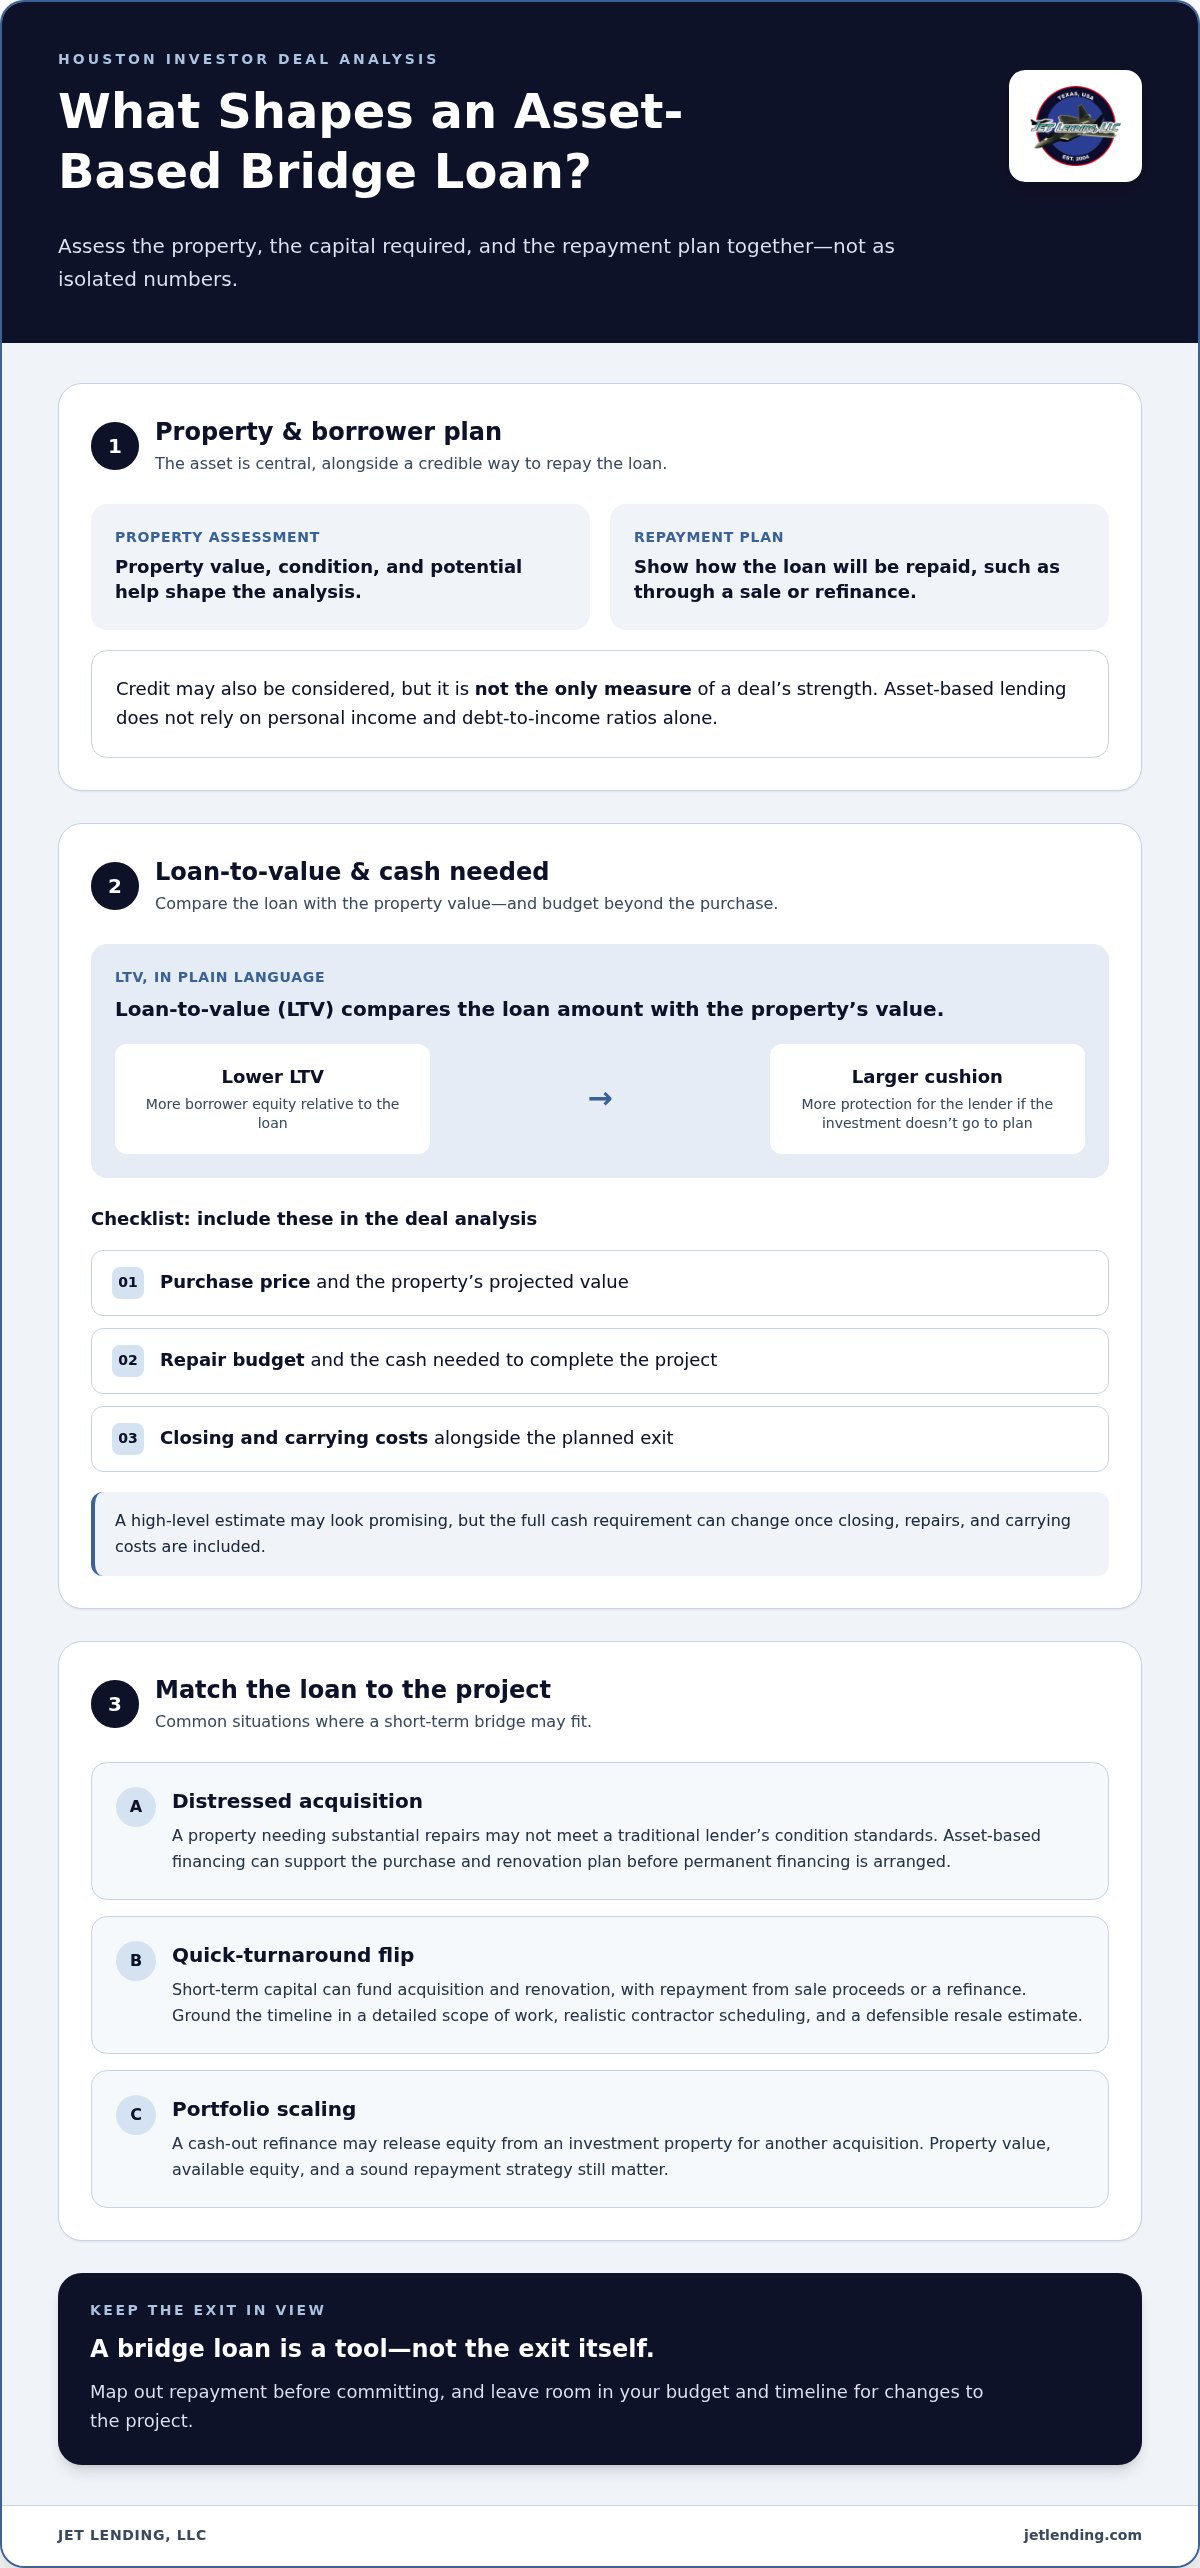
Asset-based lending evaluates the property securing the loan along with the borrower’s plan for repaying it. Property value and potential are central to the analysis, rather than personal income and debt-to-income ratios alone. Credit may also be considered, but it is not the only measure of a deal’s strength.
Loan-to-value (LTV) compares the loan amount with the property’s value. A lower LTV means the borrower contributes more equity relative to the loan, giving the lender a larger cushion if the investment doesn’t go to plan. Assess LTV alongside the purchase price, repair budget, projected value, and cash needed to complete the exit. A property that looks promising at a high-level estimate may require more investor funds once closing, repairs, and carrying costs are included.
Bridge financing can help investors pursue opportunities that need a different approach from conventional financing. Common scenarios include:
In each case, the bridge loan is a tool, not the exit itself. Map out repayment before committing, and leave room in your budget and timeline for changes to the project.
In a competitive acquisition, a 30-day closing timeline can leave room for another buyer to move first. Bridge financing gives investors a way to pursue a property while arranging the next step, such as a sale or long-term refinance. That speed can help make an offer more competitive, but funding still depends on the deal, underwriting, and closing process.
Houston investing calls for neighborhood-level analysis, not a one-size-fits-all strategy. A renovation in the Heights may involve different purchase, repair, and resale assumptions from a rental in Sugar Land. Compare recent local sales, the property’s condition, repair costs, and likely exit options before making an offer. Bridge loans for real estate investors Houston can support a plan when conventional financing doesn’t match the property or acquisition timeline.
Bridge capital can also support the buy, rehab, rent, refinance, repeat (BRRRR) strategy. Investors may use short-term financing to acquire and improve a property, then pursue a longer-term loan once the renovation and rental plan are in place. See this guide to the BRRRR method for Houston investors for a closer look at the strategy.
A proof of funds letter can help show a seller that financing is organized, but a bridge loan is not the same as cash. Be accurate about the loan’s status and timing. Don’t waive a financing contingency just to make an offer look stronger unless you understand the risks and have a financing plan that supports the commitment. Check whether your purchase timeline, property information, and expected loan structure align before setting an offer deadline.
Bridge financing describes the loan’s role: covering a short-term gap between acquisition and an exit. “Hard money” generally describes asset-based lending, so the terms can overlap. Focus on the project’s needs. An acquisition-only plan with a near-term refinance may call for a different structure than a renovation that needs more time and capital. A six-month target and an 18-month project horizon are very different timelines, so match the loan term to realistic construction, leasing, and refinance milestones. Explore hard money lending in Houston for more context, and use Jet Lending’s investment property calculator to organize a potential deal’s numbers.
A traditional mortgage is built for long-term ownership, with underwriting that typically examines the borrower’s income, credit, debts, and ability to make payments over time. A bridge loan is short-term financing for an investment property, with greater emphasis on the asset, its condition and value, and the borrower’s exit plan. Bridge loans for real estate investors Houston can be useful when a property or deadline doesn’t fit a conventional loan process.
Timelines vary by lender and transaction, but the comparison often made is about 3–7 days for bridge financing versus 30–60 days for traditional mortgage financing. These are not guaranteed closing times. A bridge loan may also accommodate an “as-is” purchase that a conventional lender might not finance in its current condition, though the property and deal still need to meet the lender’s requirements.
Traditional lenders may have property-condition standards and seasoning rules, which can limit financing for recently acquired or renovated properties. Requirements vary, so don’t assume every lender applies the same rules. An appraisal estimates value using accepted methods and comparable sales; it may not fully reflect an investor’s planned renovation upside. Bridge lenders also review the collateral and repayment plan, so present the property’s current condition and renovation assumptions clearly rather than relying on projected value alone.
Compare the full borrowing cost with the realistic net profit of the opportunity, not just the headline interest rate. Include loan fees, carrying costs, renovation expenses, resale assumptions, and the possibility of delays. A higher rate is a financing cost for short-term capital, not a guarantee of a profitable deal. The strategy works only if the numbers and exit plan hold up.
Used carefully, short-term debt can help secure and improve an asset that may build long-term equity. Before committing, stress-test the budget: consider what happens if repairs cost more, the sale takes longer, or the refinance proceeds are lower than expected.
Bridge loan qualification starts with the property and the plan to repay the loan. After-repair value (ARV) estimates what a property could be worth once renovations are complete. Lenders may consider ARV alongside the purchase price, repair scope, property condition, and exit strategy. Build your estimate from comparable renovated properties with similar location, size, and features, not from the most optimistic sale price you can imagine.
For bridge loans for real estate investors Houston, prepare a clear deal package with the signed purchase contract, a detailed scope of work, and a realistic exit strategy. Your track record may also inform a lender’s view of the project. Be ready to describe relevant experience and explain how you’ll manage the work, timeline, and repayment.
Use the ARV formula for real estate to estimate value from comparable renovated properties, then account for the renovation budget and likely selling or refinancing costs. Conservative assumptions make it easier to see whether the deal still works if repairs take longer or the final value comes in below target. For Houston properties, use comparisons from the relevant area rather than treating citywide prices as a reliable guide to a specific neighborhood.
Model the whole project, not just the purchase. Enter the loan amount and terms, then include renovation expenses, holding costs, origination fees, interest, and expected exit costs. Compare projected sale or refinance proceeds with the amount needed to repay the loan. Jet Lending’s investment property calculator can help organize these inputs. Use the result to identify assumptions that need a closer look, such as repair costs, project duration, or the expected resale price. This guide to analyzing a fix-and-flip deal offers more detail on evaluating project assumptions.
Choose a primary payoff route before closing. You might renovate and sell, or hold the property as a rental and pursue a refinance into a debt-service coverage ratio (DSCR) loan. A DSCR loan evaluates rental income in relation to the property’s debt obligations, subject to its qualification requirements.
Build a Plan B, too. If the sale takes longer or refinancing doesn’t proceed as expected, identify a practical alternative, such as adjusting the timeline or selling under different market conditions. A credible backup helps you prepare for uncertainty and keeps repayment at the center of your deal analysis.
Jet Lending provides short-term, asset-backed financing for real estate investors, including funding for property acquisitions and rehabilitation. For Houston investors, the process begins with the property and its investment plan. A well-prepared deal makes it easier to discuss the project’s costs, risks, and repayment route.
The process is straightforward:
Use the review to test your assumptions, too. If the repair budget, property value, or exit timeline needs more work, addressing it early can help you make a more informed decision.
Jet Lending has worked with Texas real estate investors since 2004. Its asset-based approach centers on the property and investment plan, helping borrowers think through deal structure, local property considerations, and potential risks before committing. The aim is to have a practical conversation about what the numbers support, rather than rely on a one-size-fits-all answer. Bring the details of the opportunity, including its challenges as well as its potential.
You can prepare before you have a property under contract. Organize your investment goals, experience, and general financing needs so you’re ready to assess an opportunity when one appears. For a specific offer, gather the purchase contract, property information, and a clear repayment plan. A proof of funds letter may support your offer when provided during the financing process; it is not a substitute for final loan approval or a guarantee of funding.
Bridge loans for real estate investors Houston can help turn a time-sensitive opportunity into a well-planned investment when the property, terms, and exit strategy align. Use Jet Lending’s investment property calculator to refine your deal analysis, then prepare the details of your project for review.
Bridge financing can help investors pursue a property on a short timeline, but speed works best when the numbers and payoff strategy are sound. Compare the property’s current condition with its realistic after-repair value, account for the full project costs, and decide whether you’ll repay the loan through a sale or refinance.
For bridge loans for real estate investors Houston, focus on the fit between the asset, loan terms, and exit plan. A well-prepared deal gives you a stronger foundation for making an offer and managing the project from acquisition through payoff.
Jet Lending provides short-term, asset-backed loans for real estate investors and has worked with Texas investors since 2004. Use the investment property calculator to organize your assumptions and see how the numbers align with your goals.
Start with a thoughtful plan. Prepare your property details, project budget, and exit strategy, then take the next step with Jet Lending.
There isn’t one rate that applies to every Houston bridge loan. Pricing depends on factors such as the property, loan amount, leverage, project timeline, and planned exit. Investors searching for bridge loans for real estate investors Houston should compare the full terms, not just the interest rate. Review how interest, fees, repayment timing, and any extension provisions affect total borrowing costs and projected returns.
Credit is one factor that may be considered, but it does not tell the whole story of an investment deal. The property’s value, available equity, investment plan, and exit strategy are also important to the analysis. Prepare a clear deal package and be ready to explain how you’ll repay the loan. A credit challenge does not automatically determine whether a deal is viable, but the overall project still needs to make sense.
Closing time depends on the property, completeness of the deal information, underwriting, title work, and other transaction details. To keep a Houston project organized, gather the purchase contract, property information, repair plans, and exit strategy early. Build the expected closing date into your offer timeline and account for the steps needed to complete the transaction.
Bridge loans commonly require the investor to contribute equity, though the amount depends on the loan structure and property analysis. Loan-to-value, or LTV, compares the loan amount with the property’s value. If the loan covers only part of the acquisition or project costs, you’ll need funds for the remaining amount and other expenses. Include that contribution in your deal budget before making an offer or committing to repairs.
A bridge loan describes the financing’s purpose: covering a short-term gap between an acquisition and an exit, such as a sale or refinance. Hard money typically describes asset-based lending, so the terms can overlap. Look beyond the label and compare what the loan can fund, its duration, costs, repayment requirements, and how the property is evaluated. Choose a structure that fits the project and a realistic payoff plan.
Prepayment penalties depend on the specific loan agreement. Don’t assume you can repay early without added cost, or that a penalty automatically applies. Before signing, review the loan documents for any early payoff provisions, minimum interest period, or other repayment conditions. These terms matter if you expect to sell or refinance quickly because they affect projected net proceeds and the timing of your exit.
A lender needs to assess the property securing the loan, but the valuation process can vary by transaction. An appraisal may be required, and other valuation methods may also be considered. Be prepared to provide property details and information supporting your value assumptions, including relevant comparable sales and renovation plans. For a Houston investment, realistic local comparisons help you analyze current value and potential after-repair value.
Jet Lending’s loans are for real estate investment purposes, not owner-occupied residential mortgages. A bridge loan through Jet Lending is intended for an investment property and a defined investment plan, such as renovation followed by resale or refinance. If you’ll live in the property as your primary residence, this financing is not designed for that purpose. Keep the property’s intended use clear as you plan your financing.
Tags:

The best hard money lenders Houston TX investors consider aren’t automatically the ones with the fastest pitch or broadest claims. The right fit depends on whether the loan structure matches your...

Houston’s latest home-price data don’t tell one simple story. In August 2026, the Houston Association of Realtors (HAR) reported a median single-family home price of $330,000, down 1.5% year over...

What if the financing that gets you into a Houston investment property becomes the biggest risk to getting out? A bridge loan can connect an acquisition or rehabilitation project to its next...